
 1052 Customer Reviews
If you are already determined to obtain an international certificate, you must immediately purchase our Financial-Accounting-Reporting exam practice. Our products have been certified as the highest quality products in the industry. If you know Financial-Accounting-Reporting training materials through acquaintance introduction, then you must also know the advantages of Financial-Accounting-Reporting. Our content and design have laid a good reputation for us. Our users are willing to volunteer for us. You can imagine this is a great product! Next, I will introduce you to the most representative advantages of Financial-Accounting-Reporting real exam. You can think about whether these advantages are what you need!
Perfect service
Financial-Accounting-Reporting exam practice is well known for its quality service! Our users are all over the world, and we use uniform service standards everywhere. Our after-sales service staff will be on-line service 24 hours a day, 7 days a week. So, whether you are purchasing Financial-Accounting-Reporting training materials, or during the study period, no matter what kind of problems you encounter, you can always contact online customer service to get the timely help. At the same time, our service guidelines have always been customer first. As long as you choose Financial-Accounting-Reporting real exam, we will be responsible for you in the end. Every Financial-Accounting-Reporting exam practice's staff member is your family they will accompany you to achieve your dream! Our company's service aim is to make every customer satisfied! Financial-Accounting-Reporting training materials are looking forward to being able to accompany you on such an important journey.
Premium content
Our company has hired the best team of experts to create the best products for you. Our team has the most up-to-date information. After analyzing the research, we write the most complete and up-to-date Financial-Accounting-Reporting exam practice. At the same time, the experts also spent a lot of effort to study the needs of consumers, and committed to creating the best scientific model for users. With the protection of content and learning methods, you will not have to worry about your exam at all. Of course, if you have any suggestions for our Financial-Accounting-Reporting training materials, you can give us feedback. Our team of experts will certainly consider your suggestions. Perhaps the next version upgrade of Financial-Accounting-Reporting real exam is due to your opinion. In order to thank you for your support, we will also provide you with some benefits.
Smooth operation
The operating system of Financial-Accounting-Reporting exam practice has won the appreciation of many users around the world. Within five to ten minutes after your payment is successful, our operating system will send a link to Financial-Accounting-Reporting training materials to your email address. After our product update, our operating system will also send you a timely message to ensure that you will not miss a single message. After you use Financial-Accounting-Reporting real exam,you will not encounter any problems with system . If you really have a problem, please contact us in time and our staff will troubleshoot the issue for you. Financial-Accounting-Reporting exam practice's smooth operating system has improved the reputation of our products. We also received a lot of praise in the international community. I believe this will also be one of the reasons why you choose our products.
Admission Test Financial-Accounting-Reporting Exam Syllabus Topics:
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Select Transactions | 25% - 35% | - Accounting and Reporting Transactions
|
| Topic 2: Financial Reporting | 30% - 40% | - General Purpose Financial Reporting
|
| Topic 3: Select Balance Sheet Accounts | 30% - 40% | - Assets, Liabilities and Equity
|
Admission Test Certified Public Accountant (Financial Accounting & Reporting) Sample Questions:
Which of the following information should be included in Melay, Inc.'s 1992 summary of significant accounting policies?
- A. Business segment 1992 sales are Alay $1M, Belay $2M, and Celay $3M.
- B. During 1992, the Delay component was sold.
- C. Property, plant, and equipment is recorded at cost with depreciation computed principally by the straight-line method.
- D. Future common share dividends are expected to approximate 60% of earnings.
Correct Answer: C 🗳️
During 1990, Fuqua Steel Co. had the following unusual financial events occur:
* Bonds payable were retired five years before their scheduled maturity, resulting in a $260,000 gain. Fuqua has frequently retired bonds early when interest rates declined significantly.
* A steel forming segment suffered $255,000 in losses due to hurricane damage. This was the fourth similar loss sustained in a 5-year period at that location.
* A component of Fuqua's operations, steel transportation, was sold at a net loss of $350,000.
This was Fuqua's first divestiture of one of its operating segments.
Before income taxes, what amount of gain (loss) should be reported separately as a component of income from continuing operations in 1990?
- A. $260,000
- B. $(255,000)
- C. $(350,000)
- D. $5,000
Correct Answer: D 🗳️
Thorpe Co.'s income statement for the year ended December 31, 1990, reported net income of $74,100. The auditor raised questions about the following amounts that had been included in net income: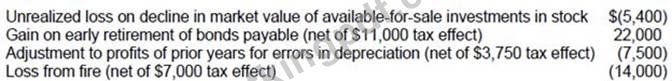
The loss from the fire was an infrequent but not unusual occurrence in Thorpe's line of business.
Thorpe's December 31, 1990, income statement should report net income of:
- A. $66,100
- B. $65,000
- C. $87,000
- D. $81,600
Correct Answer: C 🗳️
The following information pertains to Aria Corp. and its divisions for the year ended December 31, 1988: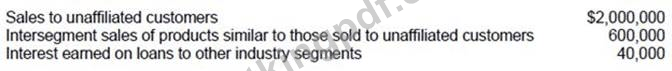
Aria and all of its divisions are engaged solely in manufacturing operations. Aria has a reportable segment if that segment's revenue exceeds:
- A. $204,000
- B. $260,000
- C. $264,000
- D. $200,000
Correct Answer: B 🗳️
Grum Corp., a publicly-owned corporation, is subject to the requirements for segment reporting. In its income statement for the year ended December 31, 1991, Grum reported revenues of $50,000,000, operating expenses of $47,000,000, and net income of $3,000,000. Operating expenses include payroll costs of $ 15,000,000. Grum's combined identifiable assets of all industry segments at December 31, 1991, were $40,000,000.
Cott Co.'s four business segments have revenues and identifiable assets expressed as percentages of Cott's total revenues and total assets as follows: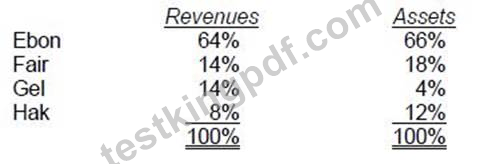
Which of these business segments are deemed to be reportable segments?
- A. Ebon and Fair only.
- B. Ebon, Fair, and Gel only.
- C. Ebon only.
- D. Ebon, Fair, Gel, and Hak.
Correct Answer: D 🗳️






Ulysses -
Very helpful exam material for Financial-Accounting-Reporting certification exam here at PrepAway. Bought the pdf file and practise exam software and it helped me score 90% marks in the exam. Great work team PrepAway.